
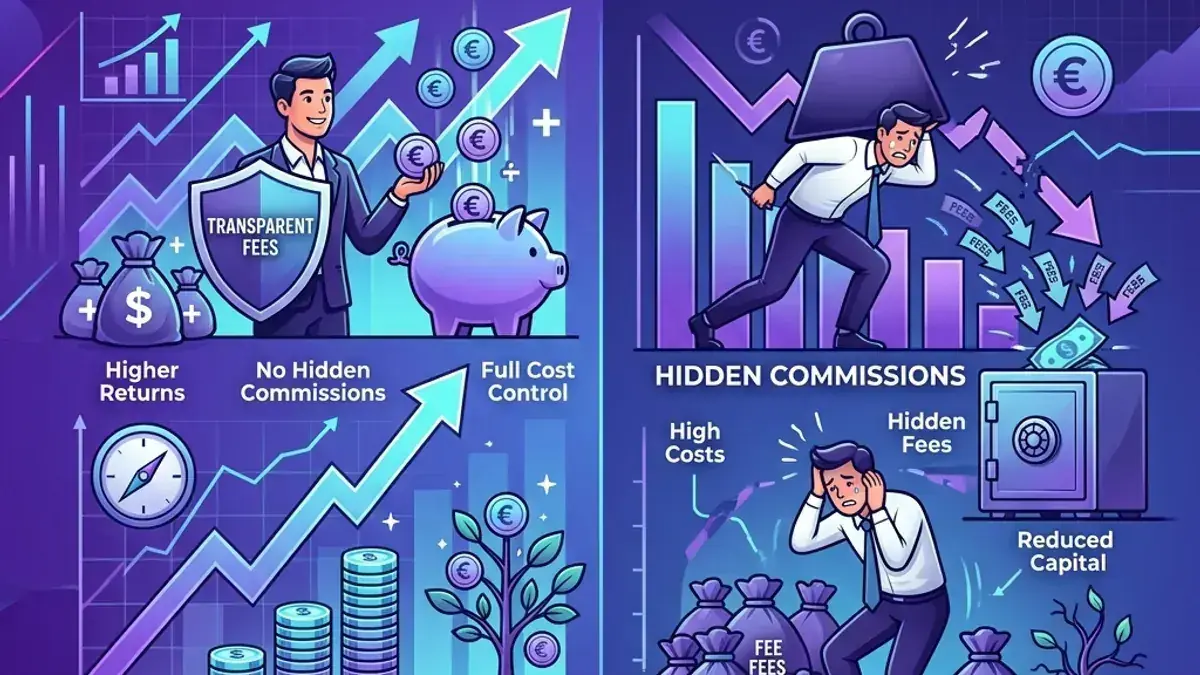
Did you know that with a traditional German pension plan (Bruttopolice), thousands of Euros from your savings never actually make it into your investment? Instead, they go directly to the broker as upfront commissions. Here is how "Nettopolicen" (fee-based plans) eliminate this hidden cost.
What is a Bruttopolice?
In Germany, the traditional insurance system relies on commission-based contracts, known as Bruttopolicen. When you sign up for one of these with a bank or a standard broker, high sales and acquisition commissions are built directly into your monthly premium (typically around 2.5% to 4% of your total lifetime contribution).
By German law, these high acquisition fees are subtracted from your contributions during the first five years of the contract. This process (called Zillmerung) means that in the important early years of saving, very little of your money is actually working or earning compound interest.
What is a Nettopolice?
A Nettopolice is a fee-based (commission-free) insurance contract. These plans contain zero built-in sales commissions or agent kickbacks. Every single Euro you save flows directly into your chosen ETF portfolio from the very first month.
Instead of paying hidden fees inside the contract, you pay the broker (acting as your fiduciary representative) a transparent, one-time fee for setting up and advising on the contract. This setup and advisory fee typically ranges from €1,000 to €1,500, depending on the complexity. Keeping the advice and the product separate is the key to maximizing your long-term returns.
The Mathematics: An Example
Let's look at a typical calculation. If you save €300 monthly over a 35-year term at an average gross market return of 6% per year:
- Traditional Bruttopolice: High upfront sales costs (often 2.5% of the total contribution sum, i.e. €3,150) and ongoing total charges (e.g. around 1.5% of asset values annually) leave you with approximately €290,000 at retirement.
- Fee-Based Nettopolice: With zero acquisition commissions and very low total ongoing costs including ETFs (around 0.5% to 0.6% annually), your retirement fund grows to approximately €335,000.
Even after deducting the one-time advisory fee, you walk away with an advantage of over €40,000 more in your retirement pocket, purely because your money was allowed to compound undisturbed.
Fiduciary Standards for Expats
Expats moving to Germany are often unfamiliar with the high commission structures of German retail banks. As your legal fiduciary representative, I provide you with transparent, commission-free Nettopolicen that protect your mobile capital.
Fee-Based Accounts Outperform
For international professionals in Germany, Nettopolicen are the most efficient way to combine the tax advantages of a German private pension (Halbeinkünfteverfahren) with the low-cost execution of a standard ETF investment portfolio.
Checklist: Nettopolice vs. Bruttopolice
- Zero Hidden Commissions: 100% of your contributions go to work immediately.
- Maximum Compound Interest: No upfront fee deductions to stall growth.
- Full Cost Clarity: Clear separating of advising and product costs.