
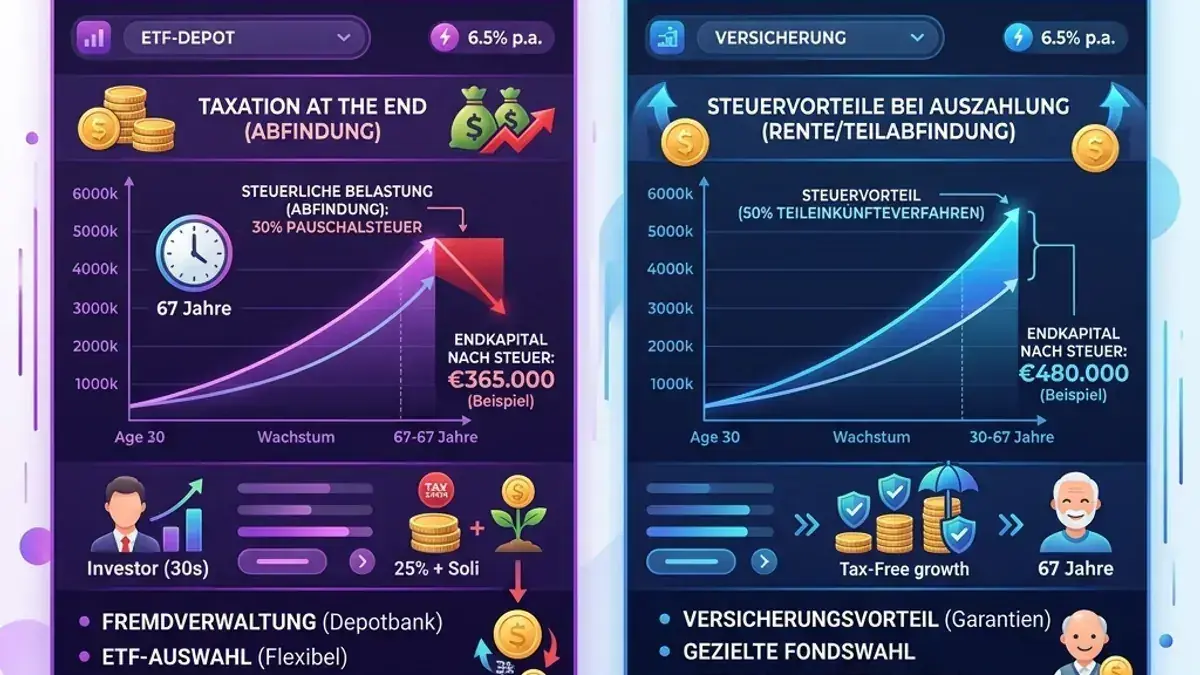
"Why should I buy a pension plan in Germany when I can just set up a free ETF savings plan with a neo-broker like Scalable?" This is a very common question. But when you look at the tax numbers of a commission-free "Nettopolice," the comparison is surprising.
The DIY Brokerage Account: Easy, flexible, but taxed heavily
A standard ETF investment account is excellent for mid-term saving (e.g., buying a home in 10 years). However, when it comes to saving for retirement over 20, 30, or 40 years, German tax law takes a heavy cut:
- Prepayment Tax (Vorabpauschale): With accumulating ETFs you pay tax each year on part of your unrealized gains. It is credited when you sell later, but the money is missing from your compounding for years.
- Rebalancing Costs: If you sell an ETF to buy a different one (e.g., to shift to bonds before retirement), capital gains tax is due right away: 26.375% (Abgeltungsteuer including solidarity surcharge). For equity ETFs with at least 51% equities, the 30% partial exemption (Teilfreistellung) brings the effective rate down to around 18.46% of the gain.
- Payout Phase: In retirement, every share you sell is taxed at the same rate. The longer you saved, the bigger the gain share in your account and the more goes to the tax office. Only with a very low income does the Günstigerprüfung let you use your lower personal rate instead.
The ETF Pension Plan (Nettopolice) as a Tax Shield
A commission-free Nettopolice places your ETF depot inside a tax-sheltered insurance wrapper. This changes the tax rules in three major ways:
- Tax-Free Swaps: You can switch and rebalance your ETFs inside the plan as often as you want. No capital gains tax is triggered. This allows your entire compound interest to remain invested and grow.
- The Halve-Income Method (Halbeinkünfteverfahren): If your plan runs for at least 12 years and you take the payout after age 62, only 50% of the gains are taxed. Combined with a 15% insurance tax discount, only 42.5% of your gains are taxed at your personal income tax rate, saving you thousands compared to a brokerage account.
- Lifetime Pension Option: Unlike a standard account that can be depleted, a private pension guarantees a lifelong monthly payment. The tax on this lifelong pension uses the highly favorable Ertragsanteil tax rate (where e.g., at age 67, only 17% of the payout is subject to tax).
Worked Example: €100,000 Gain at Payout
Say your equity ETF holds a gain of €100,000 when you retire. For clarity I leave out church tax, the saver's allowance and product costs.
- Brokerage account: After the partial exemption, €70,000 is taxable. At 26.375% you pay around €18,460.
- Nettopolice (12-year term, payout from age 62): €42,500 is taxable at your personal income tax rate. At 25% that is €10,625, at 35% around €14,875, at 42% around €17,850.
So the policy comes out ahead as long as your marginal tax rate in the payout year stays below roughly 43%. Because a lump sum raises your income in that year, timing matters: a year with little other income, or taking the money as a lifelong pension, often lowers the tax bill a lot. In a consultation we run the numbers with your own figures.
Which Option is Best For You?
It is not an either/or choice. A smart wealth strategy combines both:
- DIY Brokerage: For liquid money that you might need to access before retirement (emergency funds, large purchases).
- Nettopolice: As the core foundation of your retirement plan. The tax savings easily outweigh the low product costs of a Nettopolice over long periods, resulting in a higher net income in retirement.
Avoid Commission Traps
Warning: These tax advantages only translate into wealth if you use a commission-free Honorartarif (Nettopolice). Traditional commission-loaded plans sold by local banks will consume your tax advantage in upfront sales charges. With a Nettopolice no acquisition commission is offset against your first contributions, so your money is invested in the funds from the first month.
Tax Optimization is Key
To build wealth in Germany, you must minimize your tax drag. The Nettopolice is the most efficient tax-sheltered vehicle available for retirement savers.
Checklist: Brokerage vs. Pension Plan
- Short to medium term (1 to 10 years): The brokerage account wins thanks to its flexibility.
- Retirement savings with 12+ years: The Nettopolice usually comes out ahead thanks to the half-income rule.
- Tax-Free Swaps: Rebalance ETFs without triggering capital gains taxes.
- Only 42.5% Taxed: Half-income rule plus 15% partial exemption for payouts after age 62.
- Lifelong Payouts: Safeguards you from outliving your savings.