
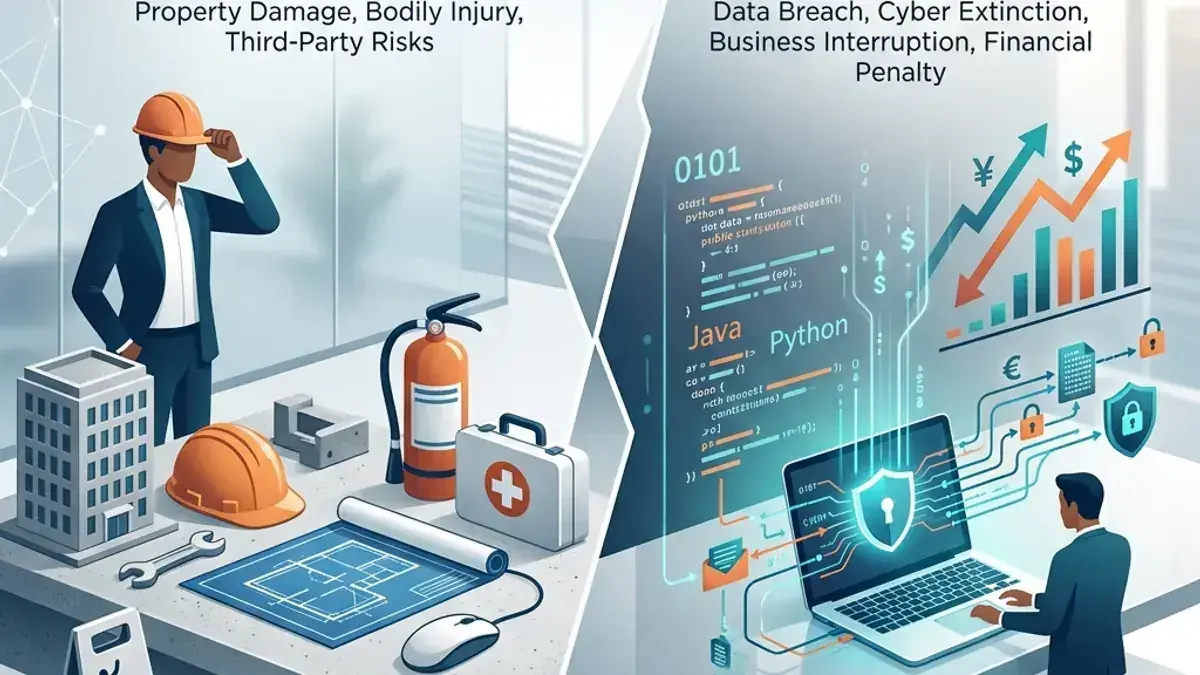
Setting up a freelance career or business in Germany as an expat is a major step. But the German liability law is unforgiving. One mistake can hold you personally and unlimitedly liable. We break down the two most critical commercial insurances: Public Liability and Professional Indemnity.
The Core Difference in a Nutshell
Under German law (BGB § 823), you are fully liable for any damages caused to third parties. These damages are categorized into different types:
- Public Liability (Betriebshaftpflicht): Protects your business against physical damages (bodily injury and property damage) and financial losses that result from them.
- Professional Indemnity (Vermögensschadenhaftpflicht): Protects your business against pure financial losses caused by errors in your professional services, consulting, or software code.
Public Liability: Protection Against Physical Accidents
Public Liability Insurance covers accidents and damage to property or people connected to your business operations or office space.
Real-world examples:
- A client visits your office or home workspace, trips over a charger cable, and breaks their leg (Bodily Injury).
- You visit a client's headquarters and accidentally spill tea on their central network switch, destroying it (Property Damage).
- Because of a server you physically damaged, the client's team cannot work for two days (Consequential Financial Loss).
Professional Indemnity: Protection Against Intellectual & Digital Errors
Professional Indemnity Insurance (Errors & Omissions) covers pure financial losses. This means no physical object was broken, and no one was physically hurt, but your client lost money due to your service or advice.
Real-world examples:
- As an IT developer, you write a bug that crashes a client's e-commerce store during Black Friday, leading to thousands in lost sales (Pure Financial Loss).
- As a management consultant, your financial analysis contains an Excel formula error, causing your client to invest in a loss-making project (Pure Financial Loss).
- As a marketing agency, you run an ad campaign but forget to secure the licensing rights for a stock photo, resulting in a copyright lawsuit against your client (Pure Financial Loss).
Fiduciary Advice for Expats:
For expat freelancers, IT professionals, and agencies in Germany, most modern tariffs package both elements into a single contract. As your neutral fiduciary representative, I analyze your specific field of activity to design a bulletproof coverage. Your fiduciary advantage means I work for you, not the insurers.
Secure Your Career Early
If you operate a business with physical office space, trade tools, or regular physical client meetings, Public Liability is your absolute base. If your product is advice, code, design, or administration, Professional Indemnity is a must-have.
Business Checklist: Which protection do you need?
- Public Liability (Betriebshaftpflicht): Standard base for businesses with physical client contact, offices, shops, or physical activities.
- Professional Indemnity (Vermögensschadenhaftpflicht): Essential for IT-freelancers, consultants, developers, and agency owners to cover financial loss.
- Combined Packages: Many modern expat tariffs in Germany package both coverages together for a complete shield.